
Historical Volatility (HV)
Historical volatility (HV) is a fundamental statistical concept in financial markets that measures the degree of variation in an asset's trading price over a specific time period. Unlike implied volatility, which reflects market expectations of future price movements, HV is calculated using actual past price data.
It measures how far a price moves away from its mean value.
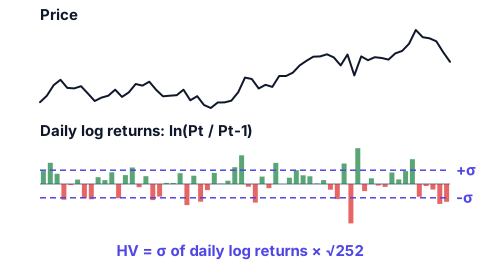
Historical volatility is typically calculated as the standard deviation of logarithmic returns of an asset over a defined period, then annualized for comparison purposes.